
In this issue of the ITS Digital Dispatch we bring you contributions by four ITS Board members.
Welcome to ITS Edinburgh!
By Patricia Longstaff

The 2025 European Regional ITS Conference is going to be a great conference and a wonderful place to wander around. You are probably like me and like to do lots of pre-planning. So I am going to share some of my ideas: some for first time ITS attendees, some for the conference itself, and some for visiting this amazing part of the world.
For New (and Former) Attendees
The conference starts with a Welcome Reception on June 29 at 18.00 and will be at Upper Apex @ Merchiston campus. This is a good place to meet the ITS Board members and other people you will run into at the conference (which will be at Craiglockhart Campus, 219 Colinton Road). So introduce yourself! There will be plenty of food and drink. You do not have to dress up for the Welcome Reception or the conference itself but wear casual clothes. For the Conference Dinner on 1 July you might dress up a bit but casual clothes are still OK.
You will be given the conference agenda with when and where papers will be presented as you register on either Sunday or Monday. You might want to sit down and think about which session you want to attend to hear a paper’s presenter. I usually mark them with a pen. But remember that the papers themselves will always be available. If you have questions about a paper you can ask it at the session where it is presented, or later to the author. Do not be shy but be respectful.
If you are still looking for a place to stay, try the ITS European Conference website https://itseurope.org/2025/.
The Conference
Presentations and papers at the conference will address some of the hottest issues in this field, including (but not limited to) AI, industry consolidation, digital literacy, roll-outs of 5G, industry regulation and techno-nationalism, and the delivery of telecommunication via satellites. The conference will run for two full days. Do not miss a minute. Save your tourist ideas for before or after the conference.
Visiting
Check the web for train rides in and around Edinburgh. I am going to take the train up North to Inverness to see Lochs and mountains . But there is plenty to see in Edinburgh. For something off the regular tourist route, try the Camera Obscura and World of Illusions. The Scottish Whisky Experience (City Center), The National War Museum,The Scottish National Gallery, the Royal Botanic Garden, and the National Museum of Scotland.
Growing Virtual Idols in South Korea
By Yoonhyuk Jung
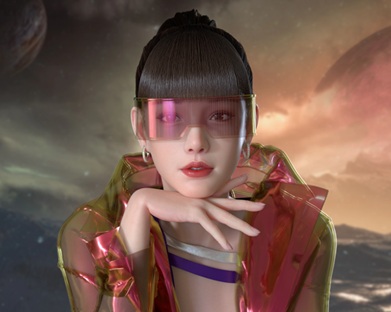
One of the most notable phenomena in the contemporary entertainment industry is the rise of “virtual idols.” In particular, South Korea stands out for the growing popularity of virtual idols, and academic interest in this topic is expected to increase accordingly. Accordingly, I would provide an analysis of the current state of South Korean virtual idols and introduce related research trends to enhance understanding of this emerging cultural phenomenon. Virtual idols go beyond mere technological advancement—they represent new possibilities for fandom culture, media consumption, and business models in the entertainment industry. Therefore, it is crucial to examine the background, success factors, and socio-cultural implications of their emergence from multiple perspectives.
The term “virtual idol” combines “virtual” and “idol,” referring to virtual humans created through software and active in cyberspace. They can be defined as “virtual celebrities” that simulate human physical features and performances based on computer graphics technology, existing as immaterial entities powered by digital data. In 1996, in Japan, an idol agency created ‘Kyoko Date’ to overcome the limitations of human idols. Later, in 2007, ‘Hatsune Miku’ emerged, gaining worldwide popularity through the combination of an electronic vocal synthesizer and an anime character, marking the starting point of the virtual idol phenomenon. In South Korea, ‘Adam’, who debuted in January 1998, is recorded as the first cyber singer.
The virtual idol market has seen rapid growth, especially during the COVID-19 pandemic, as social distancing and lockdown measures limited face-to-face concerts and traditional entertainment activities. Virtual idols gained attention through online concerts, social media, and streaming platforms.
The virtual idol market is rapidly expanding in Asia, particularly in South Korea. K-pop group Aespa experimented with virtual versions of its members, while groups such as ISAC (Isangese Idol) and PLAVE have achieved major success. For example, PLAVE is a five-member virtual boy group that debuted in February 2023. Their song ‘WAY 4 LUV’ entered the Billboard Global 200 chart, allowing them to expand their global fanbase.
In essence, I would like to introduce you to virtual idols, a burgeoning trend within the South Korean entertainment landscape.
Shutting down 3G
By Bronwyn Howell

When 3G technology was launched at the turn of the Millenium, the prospect of mobile internet – albeit at speeds recorded in kilobits – was revolutionary. 3G offered amazing new capabilities due to its internet-based packet-switching technology rather than the legacy telephony-based circuit-switching of 2G. Finally, the long-held dream of an ubiquitous anywhere, anytime, any place internet was possible. A few of us even dreamed of the day when further innovation would lead to mobile and fixed line last-mile internet access being real substitutes, rather than complements, as dominated contemporary regulatory thinking.
A mere quarter century later, that dream has become a reality, as the world embraces the new dawn of the 5G and AI era. Time then, to contemplate the 3G sunset. While it is with some nostalgia that we bid farewell to the network that hosted the Nokia 6600 (with a camera and Symbian OS), the BlackBerry Curve 8300 (helped popularise mobile email), the iPhone 3G (pioneered the smartphone era) and the early Samsung Galaxies (the Android devices leveraging 3G for its rich app experiences), the reality is that progress (i.e. 5G) demands the freeing up of the capital and spectrum devoted to the legacy networks. For most operators, the 3G sunset has well and truly passed and the 5G era has been fully embraced. Major carriers in the USA and Canada completed shutdown of their networks in 2022; in Australia this was achieved in November 2024. Most European operators will have completed the shutdown by the end of 2025. A handful, however, (Telecom Italia, until 2029; NTT Docomo, until March 2026) have announced extended operations. The sunset is still approaching, though, in emerging economies: French Polynesia, Papua New Guinea, Fiji, and New Caledonia remain heavily reliant on 3G, as are Laos, Cambodia and Vietnam, and many African countries.
New Zealand is an interesting case: its three operators have announced closure of all 3G networks on 31 December 2025. New Zealand’s shutdown comes later than many comparable countries, because it was a somewhat later adopter of the technology (2005, for the first network; the others followed in 2008 and 2009; compared to Japan 2001, Australia 2003 and South Africa 2004). In part, this was due to having only two networks initially (deploying competing GSM and CDMA standards) thereby muting competitive pressure. The third network was not deployed until 2009. Enabling the later deployers sufficient time to recoup their investments necessarily pushed out the time at which it was reasonable to decommission the legacy networks.
A co-ordinated shutdown was necessary because of extensive network sharing arrangements between the companies to allow for effective coverage across the large proportion of the country that is sparsely populated. Consequently, public management of communication is being undertaken by the Telecommunications Forum, the industry association comprised of network operators and their wholesale customers. Planning began in April 2024, when the shutdown decision was made, but communications intensity has increased lately as the deadline nears. Also prominent is advertising for the Forum’s mobile recycling scheme: more than just spectrum and capital are being recycled in this shutdown.
Bringing the prepaid model to fibre broadband
By Petrus Potgieter

South Africa’s biggest mobile networks, Vodacom and MTN, were pioneers in implementing prepaid mobile voices service in the 1990s. The effect was that the expected uptake of mobile service quickly turned out to be more than 10 times what was initially expected. This heralded a communication revolution in a country where the number of landlines never exceeded 10% of the population. Can the same be happening with fibre broadband?
The dwindling of incumbent operator Telkom’s copperline network has meant that most fixed-line connections are now optical fibre and the market is served by a multitude of operators, mostly on a voluntary open access basis. There is a vibrant reseller market and given that South Africa has good international submarine cable connections, fibre internet is relatively affordable and good. The pattern of deployment has been similar to that seen in the past for wireline telephone service – mainly for urban and affluent communities. According to a recent survey, 35% of the population lives in an area with more than one fibre operator, 19% in an area with a single operator and 46% in an area with no operator at all. As elsewhere in the world, operators’ decisions to deploy in specific areas is driven largely by their estimate of the size of the market. Although township areas generally have lower spending power than suburbs, they also have a higher population density which brings down the average cost of connecting a household.
Prepaid fibre broadband can significantly expand internet access in poorer and previously underserved communities across South Africa. By removing credit checks and long commitments, these offerings enable lower-income households – including those in townships and rural areas – to get fast internet for the first time. Providers report that uptake is strongest in township areas (like Soweto), illustrating demand for affordable uncapped data. The socio-economic benefits of this model are already visible. Cost per GB has plummeted for users who switch from mobile data to prepaid fibre. Herotel reports some township customers consume over 1 terabyte of data per month on prepaid fibre.
A prepaid fibre package provides the same high-speed, uncapped connectivity as a normal fibre line, but without the commitment. Consumers pay only for what you need, with transparency and flexibility, much like prepaid mobile airtime or electricity. The result is that broadband becomes attainable to those who might not qualify for contracts or prefer not to be tied down and/or have their service terminated for non-payment. For example, Telkom’s Prepaid Compact Fibre starter pack costs R199 (a little over $10) and includes installation plus 14 days of uncapped internet at 20 Mbps download speed. Other service providers like the Vuma Reach product offer free installation as well as a WiFi router. Herotel, a fibre and wireless provider active in small towns and townships, has rolled out a product with topups for periods as short as 7 days. Although 20 Mbps is the entry-level product on most providers, better speeds are also available.
This revolution unlocks huge opportunities for e-learning, job hunting, and small businesses in those communities, who can now afford to be online continuously at a lower cost than with mobile data. Uncapped, unthrottled fibre means students can stream lectures and families can enjoy entertainment without worrying about running out of data. Prepaid flexibility also lets households align internet spend with their income cycles; for example, buying a voucher after payday and skipping it when money is tight, thereby democratising broadband access on their own terms.